VA Loan Assumption Closing Costs in Washington State
A non-veteran buyer assumed a $503,385 VA loan at 2.25% with no monthly mortgage insurance. See an adjusted Washington worksheet covering closing costs, prepaids and seller equity.
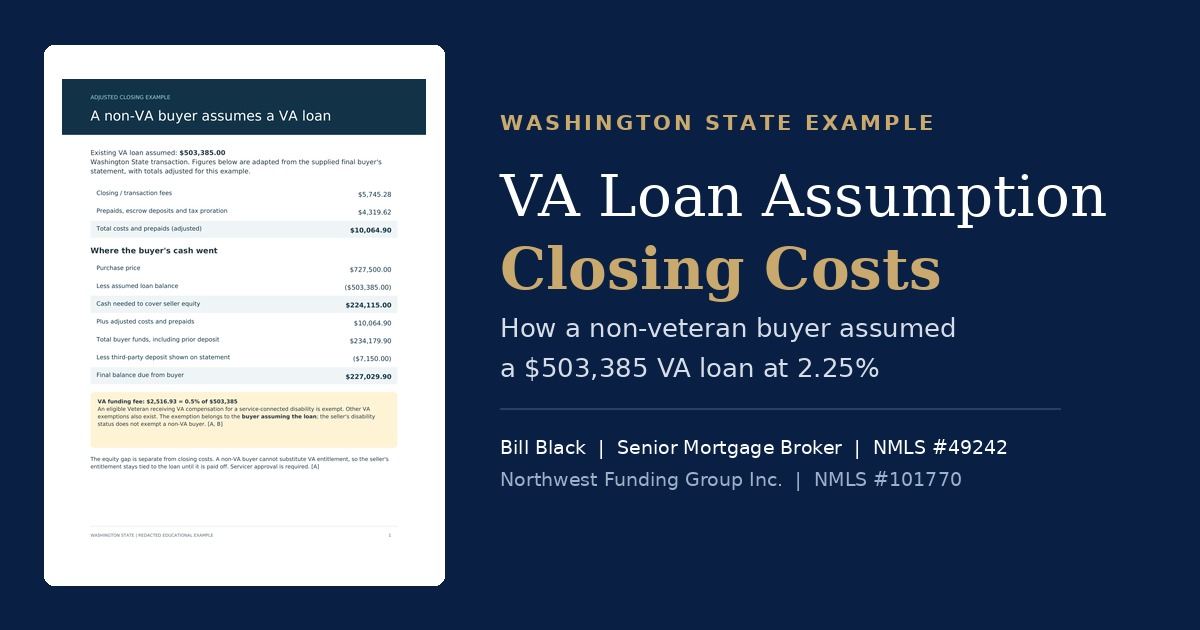
How a non-veteran buyer assumed a $503,385 VA loan at 2.25%
In this Washington transaction, a non-veteran buyer assumed a $503,385 VA loan at 2.25%, with no monthly mortgage insurance. The new-loan comparison rate Bill was using at the time was 6.99%. The buyer paid a one-time VA assumption funding fee of $2,516.93. These are historical figures for this example, not current rate offers.
Download the VA Assumption Closing Cost Worksheet
This is an adjusted educational example. The totals reflect selected charges from the closing and have been recalculated. Your transaction can include different charges, deposits or credits.
I put together a redacted, adjusted worksheet to explain the closing costs and cash needed to cover the seller's equity. The buyer paid a one-time $2,516.93 VA funding fee. This upfront charge is separate from the interest rate and is not FHA upfront mortgage insurance, known as UFMIP.
How a VA loan assumption works
With an approved assumption, the buyer takes over the existing loan obligation and its applicable terms instead of replacing that balance with a new purchase mortgage. A non-veteran still has to meet the applicable credit and underwriting requirements. Approval is not automatic.
The loan holder or its authorized servicer handles the assumption decision. A mortgage broker can help you understand the numbers and compare options, but the broker does not replace the servicer's approval process.
Closing costs and prepaids in this example
| Category | Adjusted amount |
|---|---|
| Closing and transaction fees | $5,745.28 |
| Prepaids, escrow deposits and tax proration | $4,319.62 |
| Total costs and prepaids | $10,064.90 |
The closing and transaction fees include the servicer processing fee, credit report, VA funding fee, title and escrow charges, recording costs, a Washington foreclosure prevention charge and mobile signing. The worksheet numbers each retained item and explains what it covers.
Prepaids and escrow deposits cover insurance, property taxes and amounts set aside for future bills. They are different from charges paid to process and close the assumption. For example, an annual insurance premium and an initial insurance escrow deposit can both appear because they fund different periods.
The $10,064.90 total is specific to this adjusted example. It is not an average cost, a standard percentage or a quote for another property.
The equity gap can be the biggest cash requirement
In this example, the home price is $727,500 and the assumed loan balance is $503,385. That leaves $224,115 of seller equity for the buyer to cover, before closing costs and prepaids.
| Calculation | Amount |
|---|---|
| Purchase price | $727,500.00 |
| Less assumed VA loan | ($503,385.00) |
| Seller equity gap | $224,115.00 |
| Plus adjusted costs and prepaids | $10,064.90 |
| Total buyer funds including prior deposit | $234,179.90 |
| Less deposit already shown | ($7,150.00) |
| Remaining funds due at closing | $227,029.90 |
The seller equity gap is separate from closing costs. Any plan to finance part of that gap needs to be reviewed for eligibility and approval. Do not assume the existing VA loan will cover the entire purchase price.
VA assumption funding fee and disability exemptions
For a non-exempt buyer, the VA assumption funding fee is generally 0.5% of the unpaid loan balance at transfer. On $503,385, that comes to $2,516.93 after rounding. The assumption funding fee is collected at closing and cannot be added to the assumed loan balance.
An eligible Veteran receiving VA compensation for a service-connected disability is exempt from the funding fee. Other exemption categories also exist. The exemption depends on the buyer assuming the loan. A seller's disability exemption does not transfer to a non-veteran buyer.
Servicer processing fees can vary
The worksheet uses a $300 servicer processing fee. I have recently received a report of a $700 Freedom Mortgage assumption fee with credit-card payment requested. Treat that as a reported example, not a confirmed company-wide policy. Verify the current fee and payment method directly with the servicer's assumption department.
What the Veteran seller should understand
When a non-veteran assumes the loan, that buyer cannot substitute VA entitlement for the seller's entitlement. The seller's entitlement remains tied to the loan until it is paid off. Release of liability and restoration of entitlement are separate issues, so the seller should review both before agreeing to the assumption.
Questions to ask before making an offer
- What are the current loan balance, interest rate, monthly payment and remaining term?
- How much seller equity must the buyer cover, and what sources of funds are acceptable?
- What fees, insurance prepaids and escrow deposits does the servicer require?
- What documents and approval steps apply, and is the contract timeline realistic?
- What release of liability will the seller receive, and what happens to the seller's VA entitlement?
VA loan assumption questions
- Do I have to be a Veteran to assume a VA loan?No. An eligible non-veteran buyer can assume a VA loan, subject to the applicable loan and servicer approval requirements.
- Does an assumable VA loan mean no down payment?An assumption does not erase the seller's equity. The buyer still needs an approved way to cover the difference between the purchase price and assumed balance, plus closing costs and prepaids.
- Does a 2.25% assumed rate mean a new 30 year loan?No. An assumption generally continues the existing loan terms and remaining repayment period. This example compares interest rates only. It does not estimate monthly savings because the remaining term and payment details have not been provided.
Review an assumable home in Southwest Washington
Looking at an assumable home in Vancouver, Camas, Ridgefield or elsewhere in Southwest Washington? Send me the listing and the available loan details. I can help you understand the cash requirement and compare the assumption with other financing options.
Download the VA Assumption Closing Cost Worksheet
Review My VA Assumption Numbers
Call or text 360-910-3290 | bill@billcblack.com
Learn more about VA home loans.
Educational example only. Personal information has been redacted and selected charges and credits have been removed to create an adjusted illustration. This is not the original final accounting, a Loan Estimate or a commitment to lend. The 2.25% assumed rate and 6.99% historical comparison were supplied by Bill Black and are not current rate offers or guarantees of eligibility. Actual costs and eligibility vary. Assumptions require approval by the loan holder or authorized servicer.
Official resources
- VA assumption guidance
- VA funding fee and exemption information
- Freedom Mortgage servicing fee schedule